Credit & Scoring
A borrower’s score decides the price of the loan, and the rules for producing that score are in the middle of a rewrite. This section covers the scoring models mortgage lenders are allowed to use, what rapid rescoring can and cannot do, and how tradelines, inquiries and disputes read on a mortgage credit report. It is written for the person who has to explain the number to the borrower.
6 posts, newest first
 Guide
Classic FICO vs VantageScore 4.0 Mortgage 2026: A Plain-English Guide
Classic FICO vs VantageScore 4.0 mortgage 2026: what loan officers need to know about which score model each loan program accepts and how the rules differ.
 Tracker
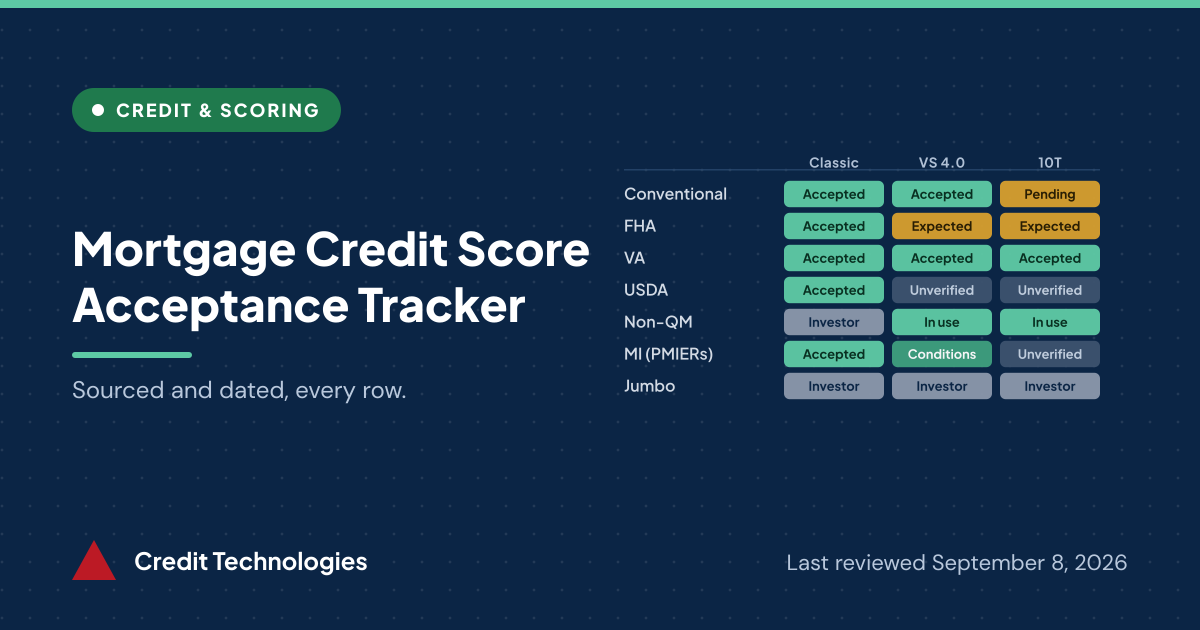
What Credit Score Do Mortgage Lenders Use? Accepted Models and Report Requirements, Updated September 2026
Mortgage lenders use one of three approved score models: Classic FICO, VantageScore 4.0, or FICO Score 10T. This tracker states what each loan program accepts today, with a source and an as-of date on every row.
 Guide
Rapid Rescore vs. Credit Repair vs. Debt Settlement
What rapid rescoring, credit repair and debt settlement each do to a credit report, who pays, how long each takes, and what it means for a mortgage.
 Guide
Tradelines in Mortgage Underwriting: A Lender's Guide
How tradelines shape a borrower's mortgage credit scores, what underwriters look for, and when a rescore can update them before closing.
 Guide
What Is a Rapid Rescore? A Guide for Mortgage Lenders
A rapid rescore updates corrected credit data in days so a lender can requalify a borrower on the new score. How it works and who orders it.
 Update
The New Center: How Smart Lenders Are Navigating the 2026 Credit & Market Shakeup
Rising credit costs, scoring model upheaval, trigger lead restrictions, and a fragile housing market are converging in 2026. Here is how lenders can find stable ground.


